What is Goodwill & Why Does it Matter
Goodwill and its role in driving value
Key Takeaways:
- Goodwill is the “how” a company performs daily operations.
- It’s an intangible asset, often resembling the “opportunity” identified by a prospective buyer.
- Goodwill is far from just a line item on a balance sheet. It’s a real and potent value driver in your business.
Goodwill is an incredibly important piece of the puzzle when talking about the sale/transfer of a business. Potential buyers or investors are not just interested in tangible assets; they also evaluate the intangible aspects that contribute to the company’s overall value. Let’s dive into what goodwill often resembles, the difference between enterprise goodwill vs. personal goodwill and its role in an entity’s valuation.
What is Goodwill?
Rule of thumb: Goodwill is the “how” a company performs daily operations. It’s an intangible asset, often resembling the “opportunity” identified by a prospective buyer. Common examples of goodwill below:
- Human capital (key executives, sales, operations, etc.)
- Processes and procedures (including use of technology/software)
- Stakeholder relations (customer concentration, key vendors, etc.)
- Company leadership and culture (arguably the most valuable form of goodwill)
The impact of goodwill on a company’s valuation can be significant.
For example: Say a company is valued at $10 million. The real estate, equipment and the working capital are valued separately at $6 million, leaving $4 million allocated to goodwill. In other words, 40% of the company’s value is comprised of goodwill. 40%!
Note: This is an example, and the value of goodwill will vary depending on factors including industry, nature, terms and conditions, etc.
Not only can goodwill represent a significant portion of company value; it’s often a key factor between a company receiving a premium or a discount on its sale price. Or in other words, price multiples. For example, assume the sale of two companies in the same industry, and of similar size (in terms of revenues.) But Company A sells at a seven multiple and Company B sells at a five multiple. Why is there a difference? Probably because Company A has better profitability. But why? Large in part due to goodwill – Company A exhibits:
- Better leadership
- Talented and engaged employees doing jobs they are well suited to perform
- Sound processes and procedures to perform their daily functions in an efficient and effective manner
- An established culture
It’s very likely that Company A is going to show stronger financial performance. This, plus the strength of their goodwill, is going to fetch a higher valuation.
Valuing goodwill is also a great KPI when measuring a company’s financial performance. We often use market multiples as a strategic planning tool. For example, if a company is valued at a multiple of 6x EBITDA, then in theory, every $1 of incremental EBITDA will result in $6 of incremental value. Pretty simple, until you put it into practice – does this mean revamping operations to improve efficiencies and margins? Does this mean better training to upskill your people? Or investing in key employees? Many, many ways to drive value. But using goodwill as your KPI is a best practice.
Personal Goodwill & Enterprise Goodwill
Goodwill comes in two flavors – personal goodwill and enterprise goodwill. What is the difference?
Enterprise goodwill is the value generated from some of the factors mentioned above that are owned by the business. Note: Not to be confused with intellectual property. It focuses on the value owned by the company, as opposed to the individual.
Alternatively, personal goodwill is value owned by an individual that either owns or is employed by a company. It is more common within companies that require specific credentials, experience and qualifications (e.g., dental practices, professional service organizations, general contractors, owner/operated companies, etc.) but is also in present in the form of customer relationships, key employees (sales, operations, etc.) or specialized knowledge/skills held by an employee.
When determining the nature of goodwill (enterprise vs. personal), a good rule of thumb is to ask yourself – “If person ABC were to leave the business, what would happen?”
Why is this important? Personal goodwill has very little, if any value in the eyes of the buyer, and more importantly, lending institutions, insurance and any other stakeholder with a financial interest in the sale of the company. And for obvious reasons, why would a company pay for value that cannot be transferred into the business?
And to clarify, the presence of personal goodwill, regardless of the form is not a “deal killer.” And in many cases, it won’t dilute the value of a company, so long as there is an agreed upon plan in place for the transition of personal goodwill into enterprise goodwill. Predominantly in the form of an earnout, i.e. a specified amount of time (months, years, etc.) that the owners of a company are contractually obligated to assist with the transition of ownership after the sale.
Conclusion
Goodwill is far from just a line item on a balance sheet. It’s a real and potent value driver in your business. It’s seen both in the broad operational strengths of the enterprise and the personal impact of individual who’ve shaped its success.
As you look towards selling or passing on your business, recognizing goodwill is important. It’s about the “how,” the people, processes, technology and culture that differentiate your company from others in the industry. Understanding these elements, along with understanding what personal goodwill vs. enterprise goodwill can materially impact both the valuation of your company, and how smoothly it transitions to new hands.
Goodwill = Value Creation
If you would like to discuss unlocking the value of goodwill in your company, contact an Adams Brown advisor.
FAQs: What is Goodwill & Why Does it Matter
In accounting, goodwill is an intangible asset recorded on the balance sheet. It is not an expense. It appears only when one company acquires another and pays more than the fair value of the target’s identifiable net assets, such as its equipment, real estate, receivables and identifiable intangibles like patents or customer lists. Goodwill a business builds internally, through its reputation, team and culture, is never recorded on its own books, even though buyers will pay for it. After an acquisition, public companies don’t amortize goodwill. They test it at least annually for impairment and write it down if its value has declined. Private companies can elect a simpler alternative that amortizes goodwill over 10 years or less.
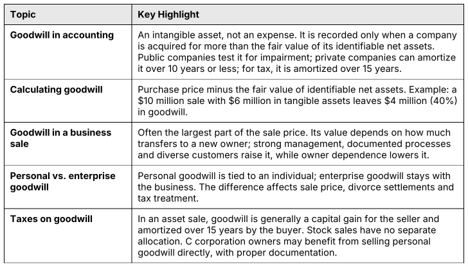
In a transaction, goodwill is the purchase price minus the fair value of the business’s identifiable net assets. For example, if a company sells for $10 million and its real estate, equipment and working capital are worth $6 million, the remaining $4 million is goodwill, or 40% of the deal. Before a sale, valuation professionals estimate goodwill the same way: they value the whole business first, usually with income-based or market-based methods built on adjusted EBITDA and industry multiples, then subtract the value of the tangible assets. Some engagements also use an excess-earnings approach, which credits goodwill with earnings beyond a normal return on the company’s assets. The result depends heavily on the company’s risk profile, growth and how dependent it is on its owner, so two businesses with similar revenue can carry very different amounts of goodwill.
Personal goodwill is value tied to an individual: their professional reputation, skills, credentials or personal relationships with customers and referral sources. Enterprise goodwill belongs to the business itself and stays with it no matter who owns it, through its brand, location, processes, workforce and systems. The distinction is common in dental and medical practices, professional service firms, contractors and owner-operated companies. It matters in several situations. In a sale, buyers and lenders put little value on personal goodwill unless there’s a plan to transfer it, such as a transition period, employment agreement or earnout. In a divorce, many states treat personal goodwill differently from enterprise goodwill when dividing marital assets. In taxes, personal goodwill sold directly by an owner can be treated differently from goodwill sold by the company. Separating the two requires a careful, well-documented valuation.
The tax treatment depends on how the deal is structured. In an asset sale, buyer and seller allocate the purchase price among asset classes and report that allocation to the IRS. The portion assigned to goodwill is generally taxed to the seller as a capital gain, which is often more favorable than the ordinary income rates that can apply to equipment recapture or inventory. The buyer amortizes that goodwill over 15 years, so the two sides often negotiate the allocation. In a stock sale, the seller simply recognizes gain on the stock, and there is no separate goodwill allocation. For owners of C corporations, selling personal goodwill directly can sometimes avoid a second layer of corporate tax. That strategy only holds up when the owner hasn’t already transferred those relationships to the company, for example through an employment or non-compete agreement, and when it’s supported by a defensible valuation. Planning the structure before signing a letter of intent gives you the most options.